VA Loan Guide for Military Families
Your VA Loan Benefit Can Do More Than You Think
A plain-language guide to using your VA loan benefit at the military duty stations we serve, from Next Season Homes, a military spouse-led team led by Bianca Hill, REALTOR®, who has used her own VA benefit five times.
VA Loan Education
VA Loan Guidance From a Family That Has Used It Five Times
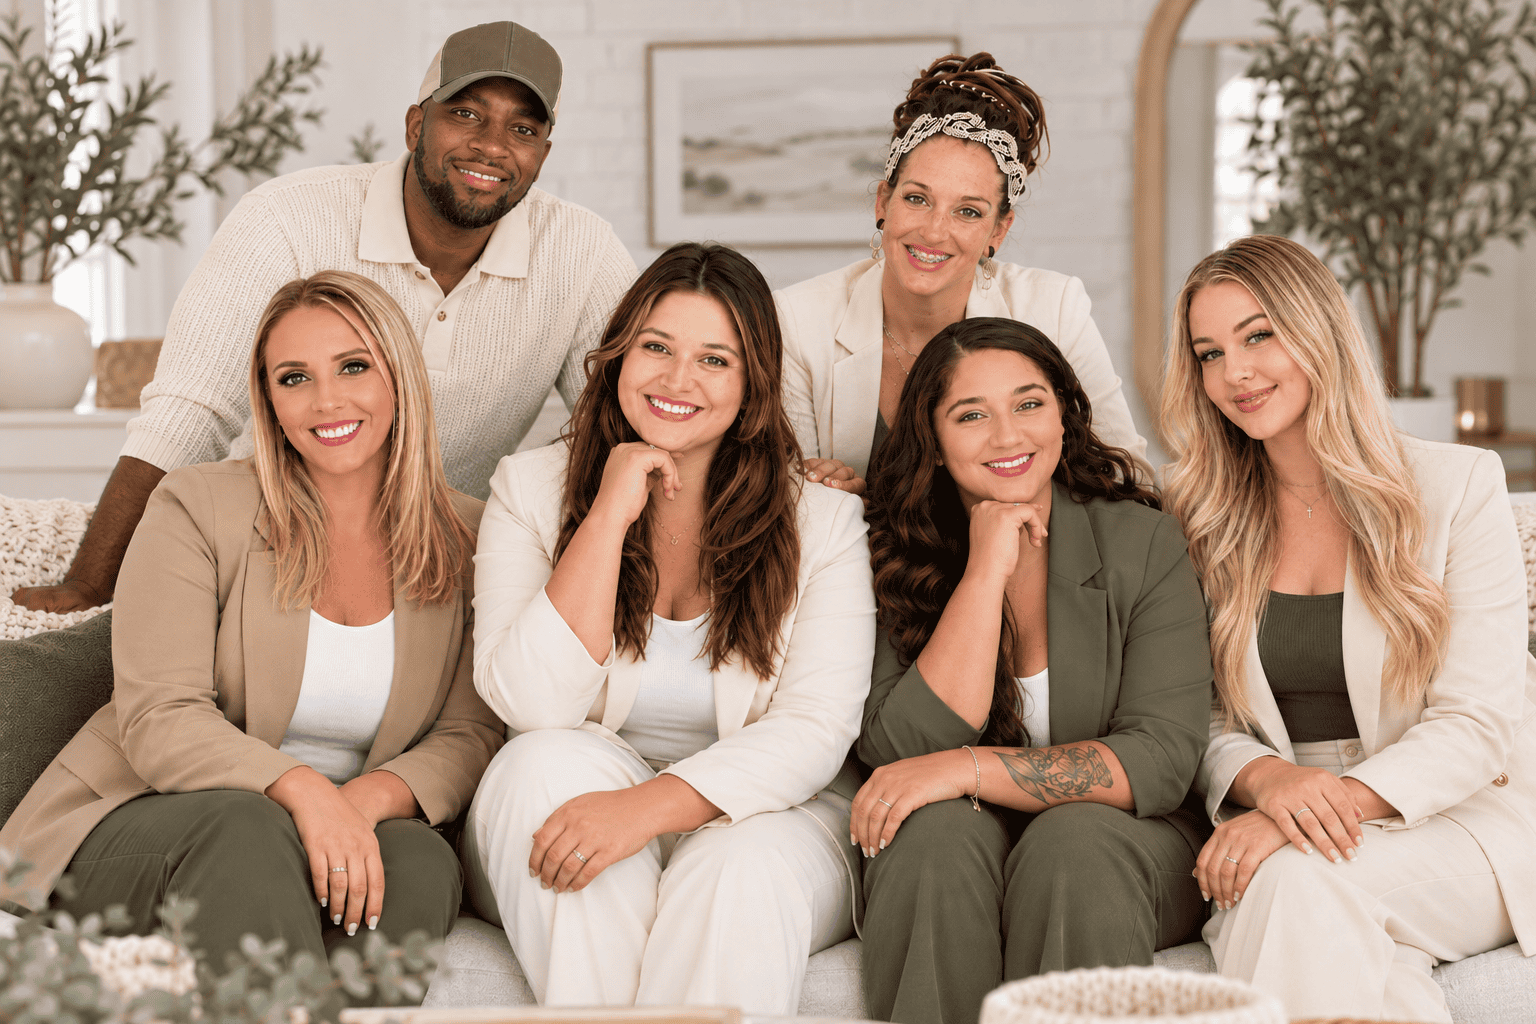
Next Season Homes is a military spouse-led team led by Bianca Hill, REALTOR®. Bianca has used her VA loan five times, starting in Hawaii nearly a decade ago. All five homes are rentals today.
That experience is behind this guide: plain language, real lessons, and a local team at the military duty stations we serve.
The Basics
What the VA Loan Actually Is
A home loan benefit backed by the U.S. Department of Veterans Affairs since 1944. The VA does not lend the money. It guarantees part of the loan, so lenders can offer better terms to eligible military families.
$0 Down
Eligible borrowers can buy with no down payment in most cases.
No PMI
No private mortgage insurance, which can mean real monthly savings.
Competitive Rates
The VA guarantee helps lenders offer strong rates to qualified borrowers.
Fee Limits
The VA limits certain lender fees for added protection.
No Prepay Penalty
Pay it off early or sell after a PCS with no penalty.
Swipe to see more →
Eligibility
Who Can Use the VA Loan
Eligibility is based on service history. These are the general groups who may qualify.
Active Duty
Typically after 90 continuous days of active service, in any branch.
Veterans
Discharged under conditions other than dishonorable, based on when and how long you served.
Guard and Reserves
After six years of service, or 90+ days of active duty under certain orders.
Surviving Spouses
Unmarried surviving spouses in certain circumstances.
Spouses Buying Jointly
Buy jointly with an eligible service member using their entitlement.
Not Sure?
Request your Certificate of Eligibility on VA.gov, or ask our team for a lender who works with military families.
Swipe to see more →
Requirements are set by the VA and can change. This is general education only. Verify your eligibility with a VA-approved lender. Official details: VA.gov eligibility.
How It Works
The VA Loan Process, Step by Step
Six steps from eligibility to keys. Our team at Next Season Homes walks you through each one, even if you are buying from your current duty station.
- 01
Confirm Eligibility
A VA lender from our list can pull your Certificate of Eligibility for you, or you can request it on VA.gov.
- 02
Get Pre-Approved
Ask our team for our list of trusted VA lenders who know military borrowers, PCS timelines, and BAH. You choose the one that fits you. Request the lender list.
- 03
Build Your Local Team
Our REALTORs® handle showings, video walkthroughs, and VA contract terms. Meet the team.
- 04
Find the Right Home
Single-family, VA-approved condos, or up to four units if you live in one. Browse homes.
- 05
Appraisal and Underwriting
The VA appraisal checks value and property standards. It is not an inspection, so book one too.
- 06
Close and Move In
Most loans include a one-time VA funding fee, with some exemptions. No PMI, and no down payment in most cases.
Swipe through the steps →
Free Download
Not Ready to Book a Call Yet?
Take the Guide With You.
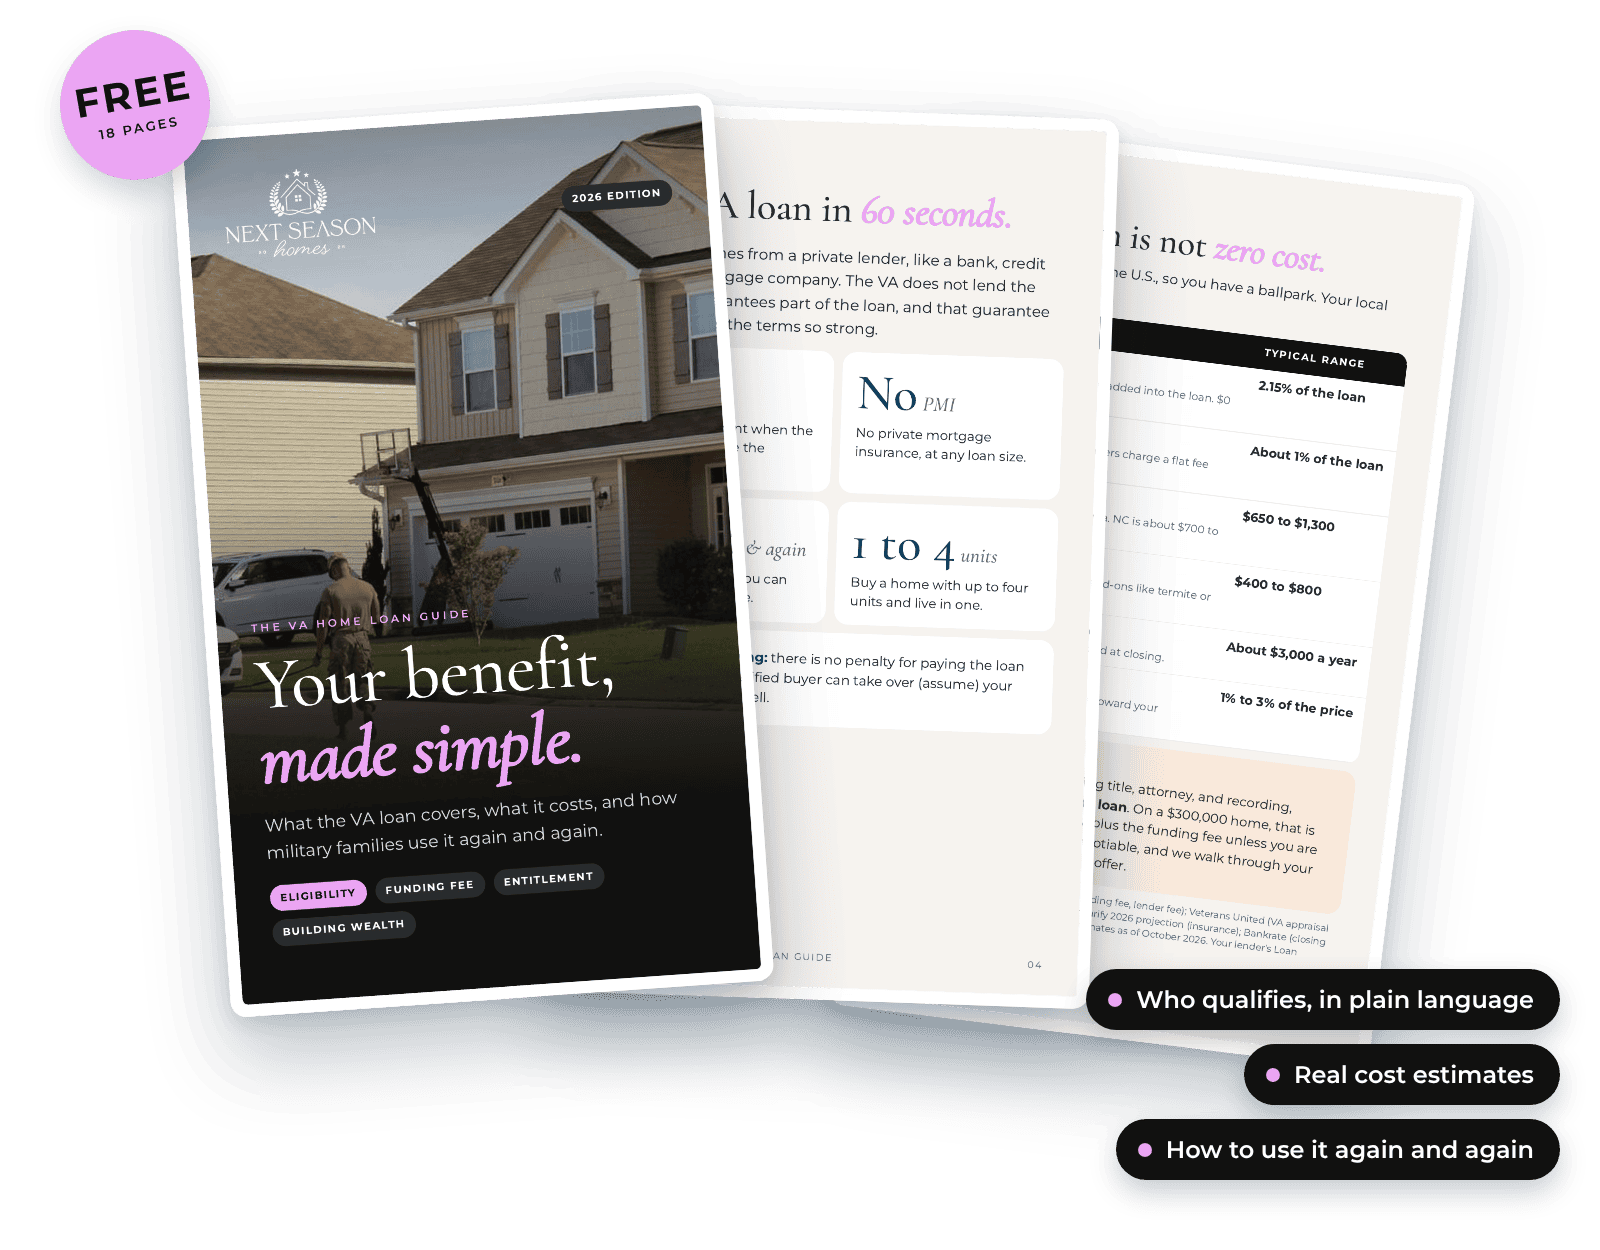
Your VA loan benefit, made simple. Who qualifies, what it really costs, and how to use it again at your next duty station. 18 pages in plain language. Save it, and share it with your spouse before your next PCS.
- Who qualifies
- Your COE
- The funding fee
- Real cost estimates
- Entitlement
- Myths vs. facts
- Building wealth
By submitting this form you agree to receive emails from Next Season Homes, led by Bianca Hill, REALTOR®. Unsubscribe anytime. View our Privacy Policy.
Beyond the First Purchase
Build Wealth Across PCS Moves
Bianca Hill and her husband bought their first home in Hawaii with a VA loan and kept it as a rental when they PCSed. Five VA purchases later, all five are rented.
It is not a secret strategy. It is an informed one, and Next Season Homes helps you plan each move with the bigger picture in mind.
Know Your Entitlement
With full entitlement, there is no VA loan limit. Start here before any purchase.
Use It Again
It is a lifetime benefit. Sometimes you can even hold two VA loans at once.
Rent or Sell at Each PCS
It depends on your equity, the rental market, and your goals. Selling during a PCS.
New Construction
Builder incentives plus VA financing can make a new home a strong option. Buying with our team.
Swipe to see more →
Common Questions
VA Loan Questions We Hear Most
Can I use my VA loan if I have already used it before?
Yes. The VA loan is a lifetime benefit, not a one-time offer. If you paid off your previous VA loan and sold the home, your full entitlement is restored and you can buy again with no down payment.
If you still have a VA loan on a home you kept as a rental after a PCS, you may be able to use remaining or bonus entitlement to buy at your new duty station. The numbers depend on your entitlement balance, the county loan limit where you are buying, and your lender's guidelines. A VA-approved lender who works with military borrowers can pull your Certificate of Eligibility and tell you where you stand before you start house hunting.
Can I have two VA loans at the same time?
Yes, and it is one of the most overlooked options for military families. If you get PCS orders and want to keep your current home as a rental, you may be able to use remaining or bonus entitlement to buy your next primary residence without paying off the first loan.
The key factors are how much entitlement you have already used, the conforming loan limit in the county where you are buying, and whether a down payment is needed if the new loan goes past your available entitlement. This is how Bianca Hill and her husband have built their own rental portfolio. It is worth talking through with a VA lender and the Next Season Homes team before you commit to anything.
Does the VA loan have a maximum loan amount?
With full entitlement, there is no VA loan limit. You can buy with no down payment at any price, as long as you qualify with your lender. Full entitlement applies to first-time VA users and to borrowers who have paid off and closed out all previous VA loans.
If you have reduced entitlement because you still hold a VA loan on another home, county conforming loan limits come into play. The VA guarantees up to an amount based on that county, and anything above it may require a down payment.
What is the VA funding fee, and who is exempt?
The VA funding fee is a one-time fee that goes to the Department of Veterans Affairs and helps keep the home loan program running for future military buyers. The amount depends on whether this is your first or a later use of the benefit and how much you put down. Putting at least five percent down lowers the fee, and ten percent or more lowers it further.
Some borrowers are fully exempt, including veterans receiving VA disability compensation, eligible surviving spouses, and active duty service members who have received a Purple Heart. If you are exempt, confirm it with your lender well before closing. The fee can also be financed into the loan, which adds interest over time. Current rates are listed on VA.gov.
Can I use the VA loan to buy a home I have never seen in person?
Yes, and many Next Season Homes clients do. PCS timelines, overseas assignments, and training schedules often mean making housing decisions from far away. The team handles in-person showings and sends video walkthroughs, written condition notes, neighborhood context, and honest feedback on anything that stands out.
The team has helped buyers stationed in Korea, Germany, Italy, and across the United States purchase homes near Fort Bragg and Fort Carson without stepping inside before closing. The VA appraisal adds an independent review of value and condition. Read their stories.
Can the VA loan be used for new construction?
Yes. VA loans can be used for new construction, and builders around the military duty stations Next Season Homes serves, including Fayetteville, Raeford, and Hope Mills near Fort Bragg, Colorado Springs and Fountain near Fort Carson, and Huntsville, Madison, and Harvest near Redstone Arsenal, often offer incentives such as rate buydowns and design upgrades. Paired with VA financing, those incentives can make a new home a strong option.
The builder's sales representative works for the builder, while the Next Season Homes team works for the buyer and negotiates directly with the builder on the buyer's behalf. See how we help buyers.
How is a VA appraisal different from a home inspection?
They do different jobs. The lender orders the VA appraisal after your offer is accepted. It confirms the home's market value and checks that it meets VA Minimum Property Requirements for safety, structure, and basic livability. The appraisal protects the lender and the VA.
A home inspection is a separate, optional step where a licensed inspector looks closely at the roof, foundation, plumbing, electrical, HVAC, and more. The VA does not require it, but Next Season Homes recommends it on every purchase, including new construction. The inspection protects the buyer.
Will sellers turn down a VA offer because of the loan type?
The answer today is more balanced than the reputation suggests. That reputation grew during the very competitive 2020 and 2021 market. In most markets now, a clean VA offer from a pre-approved buyer with solid earnest money competes well.
The appraisal is the main thing sellers watch. If a home appraises below the contract price, the VA amendment lets the buyer renegotiate or walk away. How the offer is written and presented makes a real difference, and the Next Season Homes team writes VA offers regularly at the military duty stations it serves.
What is a VA loan assumption, and should I consider it when selling?
A VA loan assumption lets a buyer take over your existing VA loan, including its original interest rate and remaining balance. When today's rates are higher than yours, that lower rate can attract more buyers and support a stronger sale price.
Assumptions need lender and VA approval, the buyer must qualify, and closing often takes 60 to 120 days. Unless the buyer is an eligible veteran who substitutes their own entitlement, your entitlement stays tied to that loan until it is paid off, which can limit your next VA purchase. Talk to us before you list.
Ready to Talk?
Let's Walk Through Your VA Loan Together
Book a free 30-minute call with Next Season Homes, led by Bianca Hill, REALTOR®. We will look at your entitlement, timeline, and next move, and share our list of trusted VA lenders. A straight answer, not a sales pitch.
Find your duty station